CIS and Making Tax Digital

CIS and MTD: what changes for a subcontractor.

If contractors take CIS off your pay, Making Tax Digital for Income Tax works on what you invoiced, not what landed in your account. Your gross pay decides when it applies to you, your quarterly updates are on it, and at the end of the year HMRC adds the CIS taken off you to your tax return for you to check. Here is how the two fit together.

Does MTD apply to you?

Your gross pay counts, before CIS comes off.

Qualifying income is turnover

HMRC tests your self-employment and property income before any expenses - your turnover. For a subcontractor that is everything you invoiced, including the CIS your contractors took off: CIS is tax paid early, not a cost.
The dates

More than £50,000 in the 2024 to 2025 tax year brought you in from 6 April 2026. More than £30,000 in 2025 to 2026 brings you in from 6 April 2027, and more than £20,000 in 2026 to 2027 from 6 April 2028.

Not just CIS work

Any other self-employed income, and any rent, are added in. Wages from a job, a pension and your share of a partnership's profit are not.

Check your date with the free MTD checker, and see HMRC's own words in its guide to qualifying income.

Through the year

Quarterly updates, on what you invoiced.

Four updates a year

From the year MTD applies to you, your software sends HMRC a summary of your income and expenses four times a year, from digital records you keep as you go.

Gross, not net

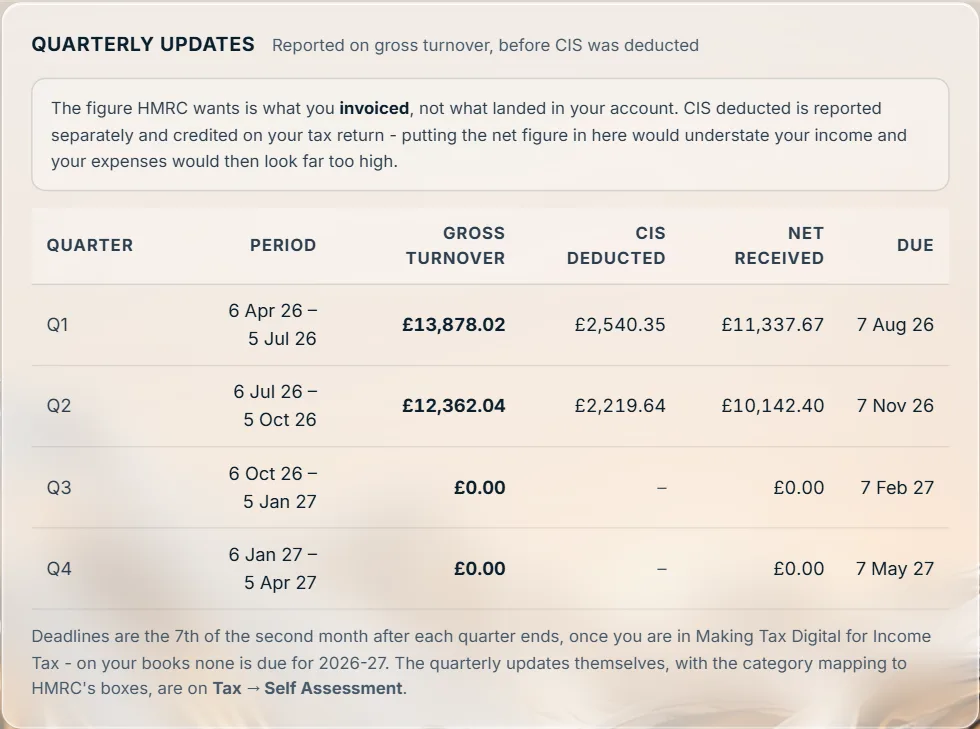
The income in an update is the gross you invoiced. The CIS taken off is not an expense and does not come off it: putting what landed in the bank would understate your income.

Your statements still matter

Every payment and deduction statement your contractors give you is your evidence of what was taken. Keep them, and chase any that do not arrive within 14 days of the end of the tax month.

At the end of the year

HMRC adds your CIS deductions. You check them.

Added for you

Under MTD, your tax return is sent through your software. HMRC adds the information it already holds, and CIS subcontractor deductions are on its list - from your contractors' monthly returns.

You must check them

Before you send the return, check what HMRC added against your own statements. A deduction a contractor never returned, or returned wrongly, will not be there - or will be wrong - until it is put right.

Then it comes back

HMRC sets the CIS against your Income Tax and Class 4 National Insurance for the year. If more was taken than you owe, the difference can come back to you.

See what may come back with the free CIS refund checker. HMRC's list of what it adds is in Submit your tax return.

What Stoneledger does

CIS and MTD in one set of books.

  • Gross on every update. Each quarterly update is worked out from your invoices, gross, with the CIS beside it rather than taken off.
  • Every statement checked against your invoices and the payments that came in. A missing or wrong one is flagged, with a chase email ready.
  • HMRC's figures beside yours. A month-by-month table to set the CIS HMRC holds against what your statements say, so a difference is found before the return, not after.
  • The year, as it builds. What has been taken off you, your tax so far, and what may come back.
Quarterly updates on gross turnover, with the CIS deducted and the net received beside each quarter
Quarterly updates on gross turnover · Sole trader sample book

CIS and Making Tax Digital, from the same invoices.

Your quarterly updates, your statements and what may come back, kept together so they always agree.

Register interest

Be first when Stoneledger opens.

Tell us a little about your business and we’ll let you know as soon as it’s ready for you. Fields marked * are required.

Business type *

Book a demo

See Stoneledger on a book like yours.

Leave your details and a time that suits you, and we’ll be in touch to confirm it. Fields marked * are required.