19% up to £50,000
A company with profits of £50,000 or less pays the small profits rate, 19%.
Corporation Tax
A limited company pays Corporation Tax on its profit: 19% on £50,000 or less, 25% over £250,000, and between the two the main rate reduced by Marginal Relief. The tax is due 9 months and a day after the company’s year ends, and the return 3 months after that. Here is what it asks of a small company, and what Stoneledger does about it.
The rates
A company with profits of £50,000 or less pays the small profits rate, 19%.
Over £250,000 it pays the main rate, 25%. In between, Marginal Relief reduces the main rate, so the tax rises gradually from one to the other.
The £50,000 and £250,000 limits are cut in proportion for an accounting period shorter than a year, and shared with any associated companies.
HMRC sets out the rates and the reliefs in its guide to Corporation Tax rates.
The dates
The tax is due 9 months and 1 day after the end of the company’s accounting period, before the return itself. If there is nothing to pay, HMRC still has to be told.
The Company Tax Return is due 12 months after the accounting period ends, sent through commercial software. The accounts go to Companies House within 9 months of the year end, or 21 months from registering for the first set.
£200 the day after, another £200 at 3 months, then at 6 months HMRC estimates the tax and adds 10% of what is unpaid, and another 10% at 12 months. Three late returns in a row turn each £200 into £1,000.
HMRC’s own pages: accounts and tax returns for private limited companies and Company Tax Returns.
What Stoneledger does
What it costs
One plan, with everything in it: the books, Corporation Tax, the accounts, VAT, both sides of CIS, payroll and journals. No price that jumps as the company grows. 30 days free, no card needed. How that compares
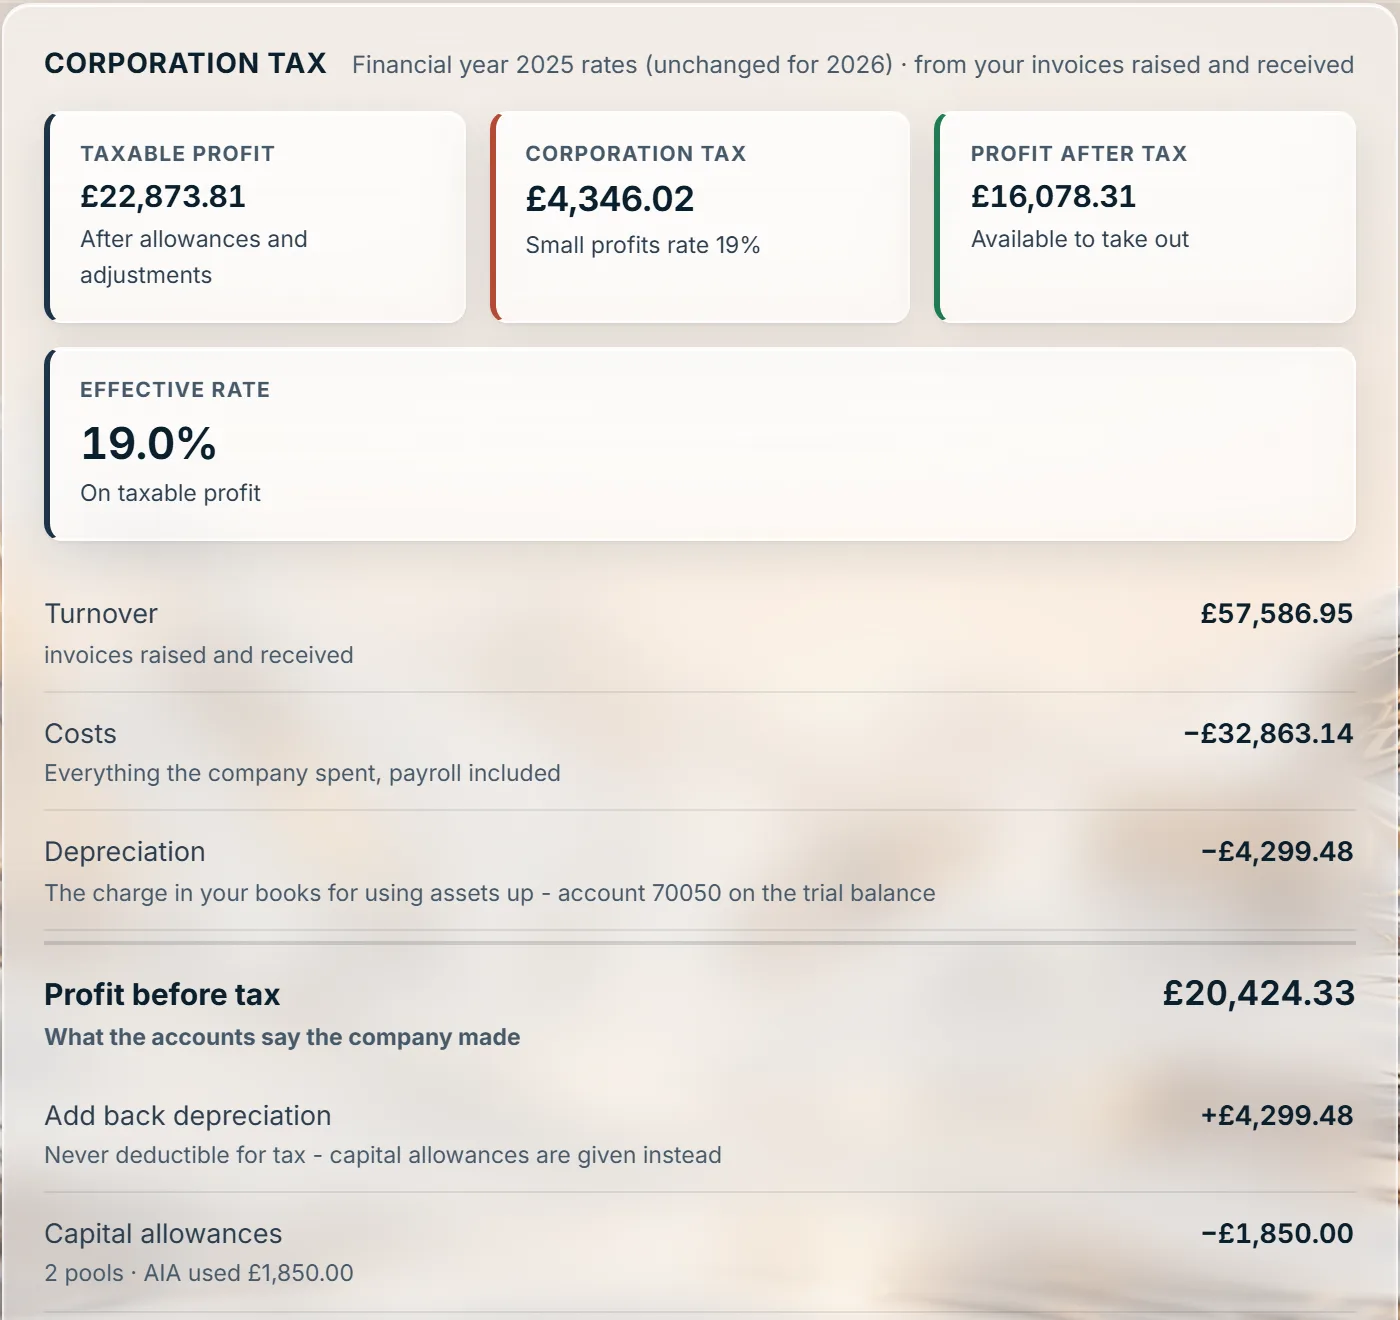
Corporation Tax as the year goes, the accounts in the format the company needs, and what is available to take out, with every number opening onto the records behind it.